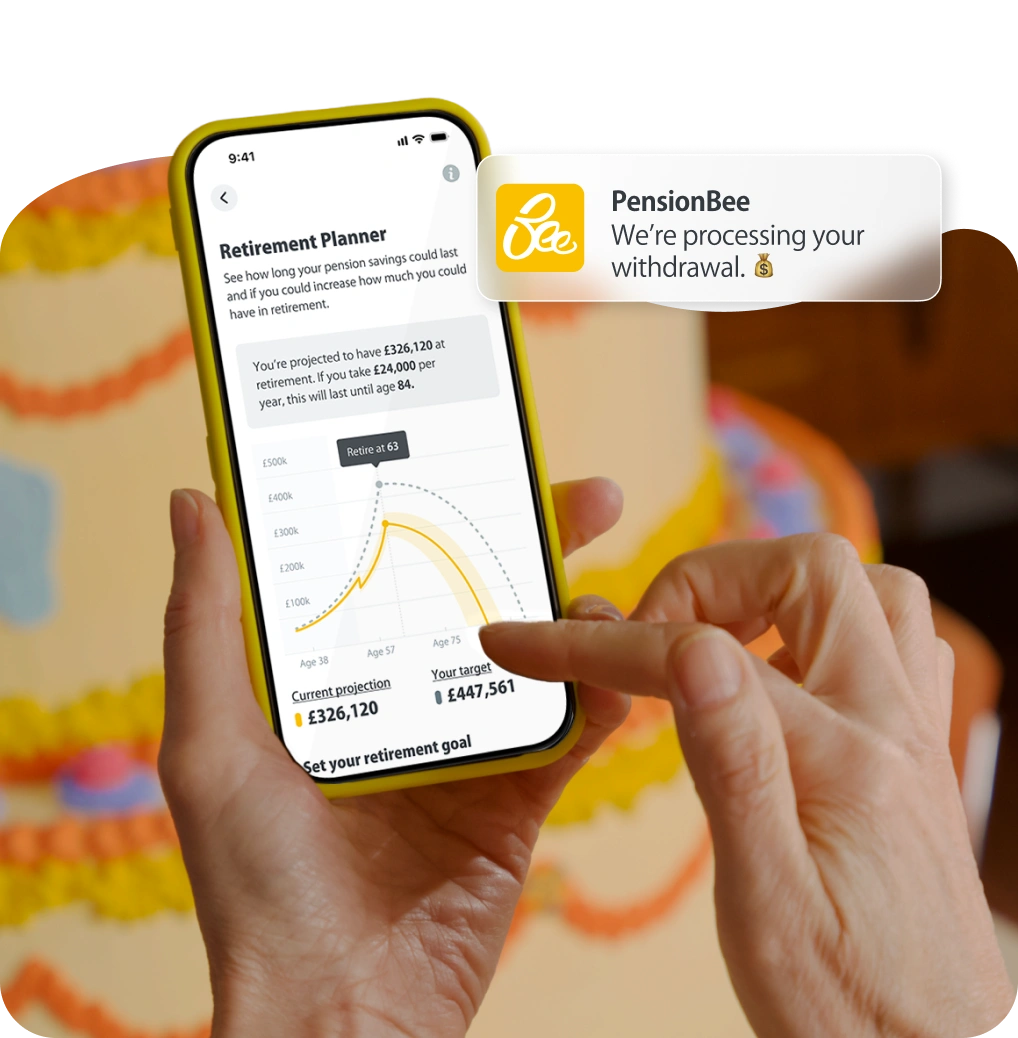


With one month to go until the Budget, Chancellor John Healey is promising a “new confidence in Britain” and a “new age of industrialisation” putting growth at the heart of his economic message. But for households, confidence starts with knowing where they stand. PensionBee research found 57% of savers aren’t confident the government will protect their pension savings in this Budget – underlining the challenge for a Chancellor aiming to get Britain investing and growing.
Maike Currie, VP Personal Finance, PensionBee, comments: “If growth is the priority, every Budget measure should face a simple test: does it give households and businesses greater confidence to plan, invest and grow?
“People make decisions about their homes, investments, pensions and retirement over decades, not political cycles. What they need from this Budget isn’t another round of short-term tinkering, but stability and a clear long-term direction of travel so they can put their money to work with confidence.”
1. Property: take control of your property wealth
The High Value Council Tax Surcharge is due from April 2028, starting at £2,500 a year on homes worth £2 million, sitting alongside a property’s existing Council Tax bill. Reports suggest the Chancellor could lower the threshold to £1.5 million.
Currie comments: “Calling it a ‘mansion tax’ disguises just how many households could ultimately be affected, particularly in London and the South East.”
What it means for your personal finances: Don’t downsize on the back of Budget rumours alone. Selling a valuable home may reduce your exposure to future property taxes and release significant capital, but buying a smaller replacement means paying Stamp Duty and other moving costs. The question is whether the long-term financial and lifestyle benefits outweigh that upfront bill.
Remember that downsizing simply moves wealth from property into cash. Sale proceeds from your main home can qualify for temporary FSCS protection of up to £1.4 million for six months, after which the usual £120,000 per person, per authorised firm applies. A savings platform can help spread larger sums across separately authorised banks, making it easier to stay within FSCS limits and secure competitive rates without managing multiple accounts yourself.
2. Pensions and IHT: certainty costs the Chancellor nothing
Pensions are once again at the centre of pre-Budget speculation, from the future of the tax-free lump sum and pension tax relief to Inheritance Tax on unused pensions from April 2027.
Currie comments: “Every Budget cycle brings fresh speculation about pensions, and that uncertainty can do damage regardless of what is eventually announced. People locking money away for decades need confidence in the rules. Greater clarity costs the Chancellor nothing, but could go a long way towards restoring trust.”
What it means for your personal finances: Don’t make irreversible pension decisions based on Budget rumours. PensionBee research found more than a quarter of savers would draw pension money earlier once the IHT changes take effect - a move that may materially impact longer-term retirement security, given longevity is unknown.
Almost a quarter (24%) said they would shift savings into ISAs or annuities – decisions that may not be right for their circumstances. By contrast, 38% of those aged 65 and over said the change would not affect them, as they have no plans to pass pensions on as an inheritance. Overall, 16% of all respondents said they did not understand the IHT implications of pensions.
HMRC has confirmed the broad framework, including that personal representatives will be responsible for reporting and paying any IHT due. One simple but important thing people can do now is ensure their expression of wish forms detailing their beneficiaries are up to date with all pension providers. Clear beneficiary information and accurate records could significantly reduce delays, confusion and stress for loved ones later on.
3. Triple Lock: move beyond ‘keep it or scrap it’
The State Pension is currently on course for a 3.9% rise next April under the Triple Lock, while its longer-term future is increasingly part of the debate around how we fund retirement and potentially social care.
Currie comments: “The Triple Lock has done an important job rebuilding the value of the State Pension, but it was a catch-up mechanism, not necessarily a forever policy. The debate needs to move beyond ‘keep it or scrap it’ and look at retirement in the round - the State Pension, State Pension age, private pension saving and social care.
“Whatever the long-term answer, reform must be signalled well in advance. People plan for retirement over decades; you can’t move the goalposts overnight.”
What it means for your personal finances: The State Pension should be the foundation of your retirement income, not the entire plan. Start by checking your own State Pension forecast and National Insurance record – so you know what you’re currently on track to receive and whether there are gaps in your record that you may be able to fill.
Then focus on the pensions you can control. If you’re employed, make the most of automatic enrolment and your employer contribution, and the opportunity to salary sacrifice before the cap comes into effect in April 2029. Many, employed and self-employed, save into a personal pension, making additional contributions flexibly when income allows, taking advantage of annual allowances (which can be carried forward) and valuable tax relief. Consider tracking down lost and forgotten pots, consolidating them to help manage retirement savings more easily – taking care not to give up valuable guarantees or benefits in the process.
4. Personal Allowance: the growing cost of fiscal drag
The Personal Allowance remains frozen at £12,570 until April 2031. In England, Wales and Northern Ireland, the 40% higher rate starts once income exceeds £50,270. HMRC estimates 7.7 million people will be higher-rate taxpayers in 2026/27 – around 1.9 million more than in 2023/24. PensionBee research found 69% of savers want the Personal Allowance unfrozen, with 43% wanting the Chancellor to act immediately.
Currie comments: “Frozen thresholds have become one of the most powerful forms of tax by stealth, quietly pulling more of people’s income into the tax net as wages and pensions rise while thresholds stand still.
“Higher-rate tax was once associated with the highest earners. As salaries rise while thresholds remain frozen, more professionals - including doctors, teachers and other public-sector workers - can find themselves dragged into higher-rate tax. Meanwhile, a 3.9% Triple Lock increase would take the full new State Pension above the £12,570 Personal Allowance. One arm of government is raising pensioners’ incomes while another claws some of it back through tax.”
What it means for your personal finances: Check which tax band you are actually in, particularly after a pay rise. Someone earning above £50,270 in England, Wales or Northern Ireland can start paying 40% tax on part of their income, while the thresholds are different in Scotland.
Pensions become even more valuable as you move into higher tax bands because contributions can attract tax relief at your marginal rate, subject to the usual rules and allowances. Salary sacrifice, where offered, can also reduce taxable pay and National Insurance - a benefit that is already set to become less generous. From April 2029, only the first £2,000 a year of pension contributions made through salary sacrifice will remain exempt from National Insurance. Any employee contributions above that will attract both employee and employer NI.
For now, fiscal drag makes it increasingly important to understand not just what you earn, but what tax band you are in and whether you’re making full use of the pension and tax allowances available to you.